Incorporating Incentive Mechanisms into Capital Planning for Sustained Participation
Written by Jakob Bennett · Sep 25, 2026
Incorporating Incentive Mechanisms into Capital Planning for Sustained Participation
Companies across multiple sectors have developed methods to merge incentive offers with established capital frameworks, and this approach supports extended periods of stakeholder involvement while maintaining financial discipline. Data from various industry reports indicate that organizations allocate portions of their capital reserves specifically for reward structures, and these allocations follow predetermined ratios that balance immediate payouts against long-term resource preservation. Researchers at institutions such as the University of Melbourne have documented how firms adjust these ratios based on quarterly performance metrics, which allows capital frameworks to absorb incentive costs without disrupting core operational funding.
Defining Core Components of the Integration Process
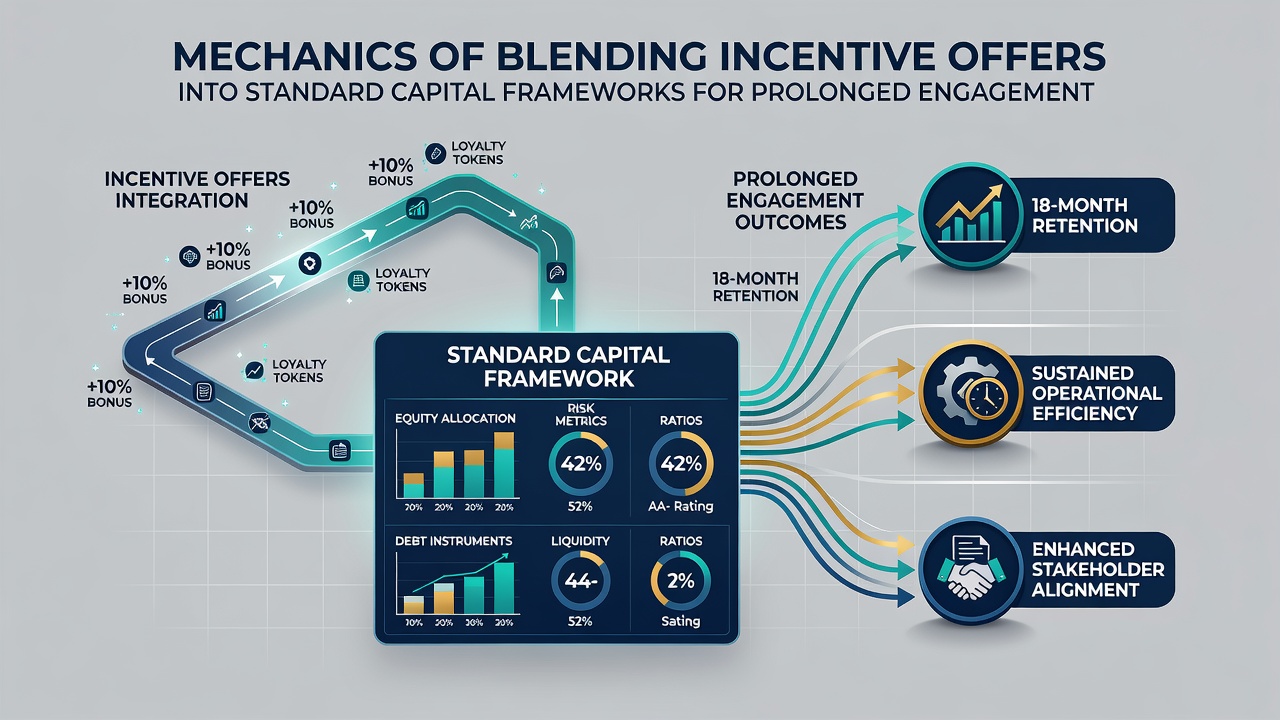
Capital frameworks consist of structured plans that govern asset deployment, debt management, and equity distribution, while incentive offers typically include discounts, loyalty credits, or performance-based bonuses. The mechanics of blending these elements require mapping each incentive type to specific capital accounts, and this mapping ensures that funds earmarked for rewards draw from designated liquidity pools rather than from emergency reserves. Observers note that successful implementations often begin with an audit of existing capital categories, after which teams identify overlap points where incentives can enhance retention without altering overall leverage ratios.
Financial models incorporate variables such as redemption rates and participation duration, and these variables feed into forecasting tools that project capital needs over multi-year horizons. According to analyses published by the Reserve Bank of Australia, organizations that embed incentive projections directly into their capital planning cycles report more consistent cash flow stability across reporting periods.
Allocation Strategies and Risk Calibration
Teams calculate the capital committed to incentives by applying percentage caps derived from historical engagement data, and these caps prevent overcommitment during periods of elevated participation. Risk calibration involves stress testing the framework against scenarios where redemption volumes spike, which reveals whether current capital buffers can absorb the load while preserving solvency metrics. Experts have observed that companies using scenario-based modeling adjust incentive scales dynamically, scaling offers upward during low-engagement quarters and contracting them when participation exceeds baseline thresholds.
One documented case involves a European retail group that restructured its loyalty program funding by diverting a fixed share of quarterly profits into a dedicated incentive reserve, and this reserve operated as a sub-account within the broader capital structure. The approach allowed the company to extend reward validity periods, which in turn correlated with measurable increases in repeat transaction frequency over subsequent reporting cycles.
Monitoring Mechanisms and Adjustment Protocols
Continuous monitoring relies on dashboards that track both capital utilization and engagement indicators simultaneously, and these dashboards trigger alerts when redemption activity approaches predefined limits. Adjustment protocols then activate, permitting managers to rebalance remaining incentive budgets across different offer categories or to extend timelines for reward fulfillment. Data compiled by Statistics Canada shows that firms employing real-time reconciliation between incentive ledgers and capital accounts experience fewer instances of unplanned borrowing to cover reward obligations.
Reporting structures require that incentive-related capital movements appear in standard financial statements under designated line items, which maintains transparency for investors and regulators alike. Integration also extends to compliance checks, where frameworks must satisfy jurisdiction-specific rules governing the treatment of deferred liabilities arising from unredeemed offers.
Implementation Across Different Organizational Scales
Smaller enterprises often begin with simplified versions of these blended frameworks by tying incentive pools to a single revenue stream, whereas larger entities distribute incentive capital across multiple business units with tailored engagement targets. In both cases, the underlying principle remains the same: incentive offers draw from capital resources in a manner that aligns with projected returns from prolonged participation. Academic papers from institutions including the University of British Columbia have examined how scale influences the complexity of these alignments, noting that mid-sized organizations frequently adopt hybrid models that combine centralized oversight with decentralized offer customization.
Conclusion
The mechanics of blending incentive offers into standard capital frameworks rest on systematic mapping, calibrated allocation, and ongoing reconciliation between financial resources and engagement outcomes. Organizations that apply these methods maintain clearer visibility into how reward expenditures affect overall capital positions, and they position themselves to sustain participation levels without compromising structural integrity. Continued refinement of these processes depends on accurate data inputs and responsive adjustment mechanisms that evolve alongside changing participation patterns.